New to Connecticut: Setting Up Home and Auto Insurance After an Out-of-State Move
What changes on your home and auto insurance when you move to Connecticut from another state, and why a licensed advisor reviews it instead of a quote calculator.
Browse all our articles related to Connecticut Requirements.

What changes on your home and auto insurance when you move to Connecticut from another state, and why a licensed advisor reviews it instead of a quote calculator.

What shapes auto insurance for New London, CT drivers - Connecticut requirements, local factors, and why an advisor reviews the details instead of an instant online quote.

A growing number of Connecticut homeowners are getting non-renewed after a carrier reviews an aerial or satellite photo of their roof. State regulators have already ruled on how far that practice can go.

Connecticut law gives you 60 days after a non-renewal notice before coverage actually ends. Here is what the notice can and cannot say, what the FAIR Plan actually covers, and how to use the window.

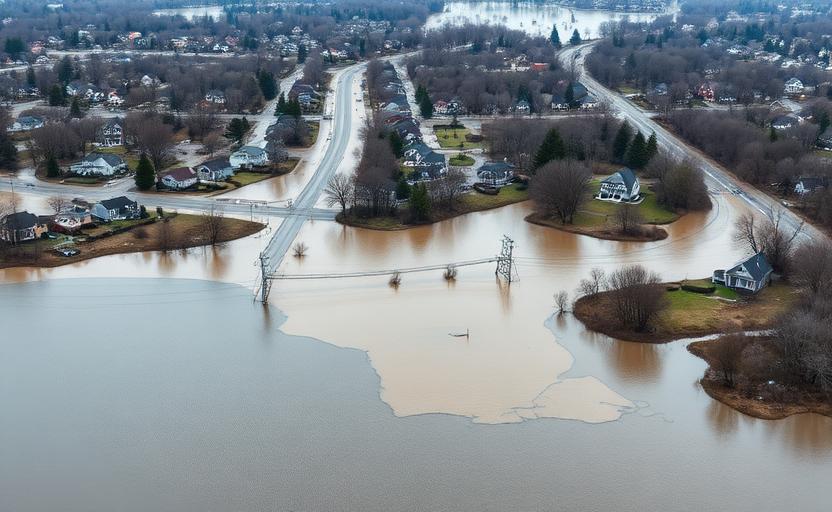
A new state-mandated notice is now landing in Connecticut homeowners and renters renewal packets, stating in plain language that flood is not covered. Here is what triggered it and what to do about it.

A municipal bid packet full of ISO form numbers and liability limits is not optional reading. Here is what "primary and non-contributory," a waiver of subrogation, and specific CGL endorsements actually mean for your certificate.

A leaking heating oil tank in Connecticut makes you legally responsible for the cleanup — including on your neighbor's property — and not every homeowners policy responds. What the state requires and what to check before it happens.

The National Flood Insurance Program's authority to write new policies expires at midnight on September 30, 2026. Here is what actually happens to a Connecticut closing if Congress does not act before then — and what does not.

Connecticut's new labor and employment law adds an uncapped workers' comp benefit, expands pay transparency liability, and makes general contractors liable for a subcontractor's unpaid wages. Here is what each means for your coverage.

Connecticut approved another statewide workers' compensation loss cost decrease for 2026. If your renewal went up anyway, the reason is specific to your business, not the state of the market.

As of July 1, 2026, Connecticut sellers must disclose flood zone, flood history, and current flood coverage on the residential property condition report. Here is what that means for your sale and your buyer's insurance.

A failed sump pump or a backed-up sewer line is one of the most common reasons a Connecticut homeowners claim gets denied — and the reason is written plainly into the policy exclusions, not hidden in fine print.

Your condo association's master policy does not cover as much as most owners assume, and when it falls short, the difference gets billed back to every unit owner as a common expense. Here is where your own HO-6 policy needs to pick up the rest.

Connecticut became the first state to give every resident an address-level climate risk score at no cost. Here is what the five risk categories actually measure, and why one independent study says the flood number runs high.

How Connecticut workers' compensation actually works for small employers: who needs coverage, how payroll and class codes drive premium, experience modification, owner elections, subcontractor certificates, and the misclassification mistakes that surface at audit.

Connecticut requires 25/50/25 liability plus uninsured and underinsured motorist coverage. Here is what those limits actually buy, where they fail a household with assets, and how to size auto limits properly.

When a permit holder must be listed, why rating follows the household rather than the title, how students away at school are handled, and why a teen driver is the right moment to revisit umbrella limits.

A family with a nanny, housekeeper, estate manager or regular groundskeeper is an employer. Here is why homeowners liability does not substitute for workers compensation, and what else follows.

Decode your Connecticut auto insurance policy and understand what coverage you have, what you need, and how to save money.

Navigate Connecticut's business insurance requirements. Learn about mandatory coverage, recommended policies, and cost-saving strategies.
Comprehensive guide to protecting your Connecticut home
🔒 Your email is 100% secure. No spam, ever.
Our expert agents are ready to help you find the perfect coverage for your needs.