New to Connecticut: Setting Up Home and Auto Insurance After an Out-of-State Move
What changes on your home and auto insurance when you move to Connecticut from another state, and why a licensed advisor reviews it instead of a quote calculator.

What changes on your home and auto insurance when you move to Connecticut from another state, and why a licensed advisor reviews it instead of a quote calculator.

How to document your home's contents before a claim, not during one - a practical checklist for Connecticut homeowners.

A growing number of Connecticut homeowners are getting non-renewed after a carrier reviews an aerial or satellite photo of their roof. State regulators have already ruled on how far that practice can go.

Connecticut law gives you 60 days after a non-renewal notice before coverage actually ends. Here is what the notice can and cannot say, what the FAIR Plan actually covers, and how to use the window.

A percentage hurricane deductible on a multi-million-dollar Connecticut shoreline home is a six-figure number most owners have never actually computed. Here is exactly when it applies, how much, and where.

Chubb, PURE, Cincinnati, Berkley One, and Private Client Select are not interchangeable. A structural comparison of how each is organized, how each handles valuation and claims, and what that actually means for a Connecticut estate.

A leaking heating oil tank in Connecticut makes you legally responsible for the cleanup — including on your neighbor's property — and not every homeowners policy responds. What the state requires and what to check before it happens.

A failed sump pump or a backed-up sewer line is one of the most common reasons a Connecticut homeowners claim gets denied — and the reason is written plainly into the policy exclusions, not hidden in fine print.

Your condo association's master policy does not cover as much as most owners assume, and when it falls short, the difference gets billed back to every unit owner as a common expense. Here is where your own HO-6 policy needs to pick up the rest.

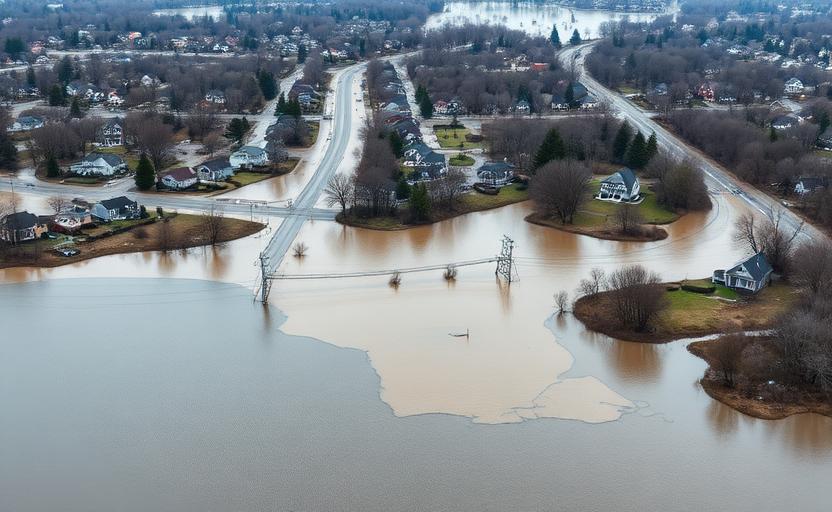
Standard homeowners policies never cover flood. Here is how to look up your own parcel's FEMA zone, where NFIP limits run out on a higher-value Connecticut home, and how excess and private flood fill the gap.

Standard homeowners forms are built for typical houses. Here is how replacement cost, ordinance or law, cash settlement, and named-storm deductibles work on a Connecticut high-value home.

Homeowners policies cap jewelry, art, and collectibles far below what most families own. A practical guide to scheduling, agreed value, appraisals, and coverage for watches, art, and wine.

A weekend house on the shoreline is underwritten as a different risk than the house you live in. How vacancy provisions, freeze warranties, named-storm deductibles, flood, rental use and umbrella coordination actually work.

A major renovation changes your rebuild cost, your occupancy status and who is liable on site. What to report before work starts, who buys builders risk, what a certificate of insurance really proves, and what to fix when the job is done.

When title moves to a trust or an LLC, the policy has to move with it. How named insured status, umbrella scheduling and lender interests decide whether a claim gets paid, and to whom.

A homeowners policy is not built for a house someone else lives in. How the dwelling fire form works, why loss of rents limits and periods matter, what tenant damage really covers, and how vacancy, lead, and short-term rentals change the analysis.

Winter weather can cause significant property damage. Learn what your Connecticut insurance covers for snow, ice, and winter storms.

Protect your Connecticut property this hurricane season. Learn what insurance covers storm damage, flood protection, and essential preparation steps.

Learn the fundamentals of Connecticut homeowners insurance, from basic coverage to additional protections you might need.
Comprehensive guide to protecting your Connecticut home
🔒 Your email is 100% secure. No spam, ever.
Our expert agents are ready to help you find the perfect coverage for your needs.